

Contribute up to $72,000
Save up to $72,000 (not including catch up) in 2026 as both employer and employee. You can even contribute alongside a traditional employer 401(k).
Get $1,500 in tax credits
You can qualify for a $500 tax credit per year for 3 years, for a total of $1,500 for including auto-enrollment.
Choose how you want to contribute
Save for retirement the way you want with traditional, Roth, or after-tax contributions, all with their own tax advantages.

Double your household savings
Add an eligible spouse at no extra cost and you may boost your contributions even more.

 100% digital setup.
Open your account online in minutes, no paperwork involved. You can even roll over an existing retirement account.
 Seamless experience.
No forms. No mailing checks. Manage and fund your account completely online. We’ll track your contributions automatically to simplify tax time.
 Automate growing your retirement.
We invest your solo 401(k) in a globally diversified portfolio, handling all the trading, rebalancing, and dividend reinvesting for you.
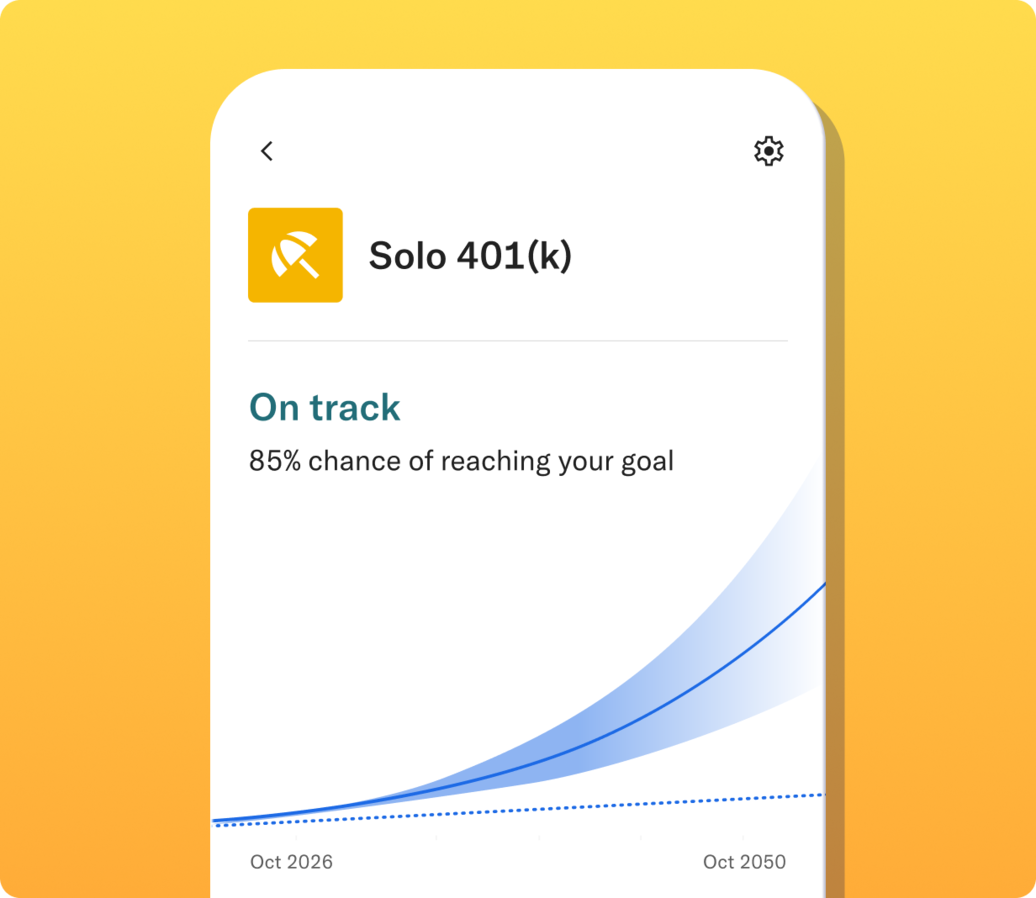

New
Grow more of your retirement
savings tax-free
Take advantage of your solo 401(k)’s higher limit by making after-tax
contributions. It’s called a mega backdoor Roth and we guide you through the
whole process in the app, helping you grow that savings tax-free.

 It’s easy to save for retirement with after-tax contributions
Take advantage of your solo 401(k)’s contribution limit by making after-tax contributions and then converting them to Roth. This can help those savings grow tax-free for qualified distributions. It’s called a mega backdoor Roth and we guide you through the whole process in the app.
Size up your options for saving while self-employed.

Ready to invest in future you?
Ready to invest in future you?